
Oriflame Franchise: Store Investment, Margins and Return Timeline in India
With nearly 49,000 franchise units operating globally, the Oriflame franchise represents one of the most widely distributed direct-selling beauty brands in the world. For a retail investor evaluating this opportunity in India, the scale of the network is not just a headline figure — it is evidence of a commercial model that has been stress-tested across diverse markets, income demographics, and consumer preferences over decades. The financial mechanics behind that scale are what this profile examines.
About Oriflame
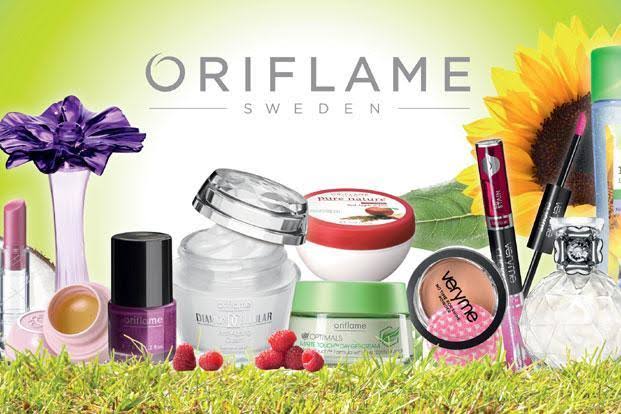
Oriflame is a Swedish cosmetics company whose product range spans skincare, colour cosmetics, fragrance, hair care, and wellness. It operates in the mid-market segment — above mass-market drugstore pricing, below prestige department store brands — which positions it squarely within the largest and fastest-growing band of Indian beauty consumers. At nearly 49,000 active franchise units globally, the brand’s consumer demand signal is unambiguous: at this scale, the product is not a speculative bet on a category trend. It is a documented, repeat-purchase proposition across millions of consumers.
The Margin and Inventory Model
Direct-selling beauty brands like Oriflame structure their economics differently from multi-brand retail. The franchisee purchases stock directly from the brand at a defined distributor price and sells at the catalogue price, with the margin between the two forming the gross profit. In the direct cosmetics category, this margin typically ranges between 20 and 35 percent on standard product lines, with higher margins available on select product categories or through volume-based incentive tiers.
Inventory in this model sits with the franchisee from the point of order. There is no consignment arrangement — the franchisee owns the stock they purchase and carries the corresponding inventory risk. The practical implication is that order discipline matters enormously: buying more than the immediate sales pipeline can absorb ties up working capital in slow-moving stock. The relatively modest entry investment at this tier limits the depth of any single order, which is both a constraint and a protection — it is structurally difficult to over-order catastrophically when total capital deployment is limited to INR 10,000 to 50,000.
Store Economics: Revenue Per Square Foot and Monthly Fixed Costs
Oriflame’s franchise model does not specify a fixed retail footprint, which separates its economics from format-dependent retail concepts. The absence of a defined square footage requirement means the franchisee’s cost structure is not anchored to rent in the way that a 500 sq.ft mall store would be. The fixed cost base is therefore determined almost entirely by staffing and operational overhead rather than occupancy — a meaningful structural difference that allows the business to reach break-even at lower absolute revenue levels than a format-dependent retail store in the same category.
The indicative monthly revenue range of INR 50,000 to INR 2,00,000 reflects the wide variance in outcomes across franchisees — which is driven almost entirely by the size and quality of the franchisee’s personal network, their activity level, and their ability to convert contacts into recurring customers. The ceiling in this model is a function of effort and network depth, not of location rent or square footage.
The Investment Breakdown and What It Covers
An entry investment of INR 10,000 to INR 50,000 at the low end of the franchise cost spectrum covers the brand licence fee — reported at INR 299 for the initial registration — opening product inventory, and basic marketing collateral. There is no store fit-out cost because there is no dedicated retail premises requirement. Working capital beyond the opening stock order is the franchisee’s responsibility to maintain, and given the direct-purchase inventory model, a small rolling reserve for reordering between catalogue cycles is a practical necessity.
Monthly ongoing costs are limited to product procurement and whatever personal marketing activity the franchisee invests in. There are no royalty payments structured into the standard model, which means the franchisee’s revenue is not subject to ongoing percentage deductions beyond the initial margin structure. For investors evaluating total cost of ownership over a 12-month period, the absence of royalties meaningfully improves the net return profile compared to traditional retail franchise formats in the same investment tier.
Seasonality and Demand Peaks in This Category
Cosmetics and personal care follow a predictable seasonal rhythm in India, with demand peaking during Diwali, the wedding season running October through February, and again around Valentine’s Day. These periods are when gifting purchases elevate average transaction values significantly — a customer who buys a single skincare product in March may purchase a three-product gift set in November. Franchisees who pre-build inventory depth ahead of these windows and have a curated gifting selection ready can capture meaningfully higher revenue per customer interaction during these months.
The leaner months — broadly June through August — see routine replenishment purchases rather than gifting uplift. Revenue in these months reflects the franchisee’s core recurring customer base rather than seasonal spikes. Franchisees who invest in building that recurring base during quieter periods — through consistent customer follow-up, new product introduction, and loyalty-based reordering — are better positioned to weather lean months than those who rely on festive peaks to carry the annual average.
Online Competition and the Omnichannel Reality
Oriflame operates its own digital channels including a catalogued online store, which means franchisees exist within an omnichannel brand ecosystem rather than competing against it. The direct-selling model is inherently relationship-dependent — Oriflame’s consumer base has historically purchased through personal recommendation and direct contact rather than anonymous online search. That relationship layer is what separates a franchisee’s sales activity from a customer browsing the brand’s website independently.
The practical risk of e-commerce cannibalisation in this model is lower than in format retail because the franchisee’s competitive advantage is personal trust, not location or display. A customer who could buy Oriflame products from any number of online channels chooses to buy from a franchisee because of the personal relationship, the product guidance, and the reliability of that contact. Maintaining that relationship quality is the franchisee’s primary defence against online alternatives, and it costs nothing beyond time and consistency.
Who This Retail Investment Suits
The Oriflame franchise suits investors whose primary asset is not capital but network: homemakers with active social connections, salaried professionals with peer groups receptive to personal care recommendations, and students with campus communities to engage. The economics are calibrated for someone who can convert personal credibility into repeat purchase — not for someone who intends to open a premises-based store and wait for walk-in traffic. Investors who approach this as a passive asset, expecting the brand to generate customers autonomously without personal outreach and relationship management, consistently remain at the lower end of the revenue range and rarely recover their investment within the estimated 6 to 12 month window.
Accepting franchise applications in 32 states & UTs
How much does it cost to open an Oriflame franchise?
The entry investment for an Oriflame franchise falls between INR 10,000 and INR 50,000, covering the initial brand registration fee and opening product inventory. There are no store fit-out or premises costs associated with the standard model, which makes it one of the lowest capital-entry franchise opportunities in the Indian beauty and personal care category. Working capital for reordering should be budgeted separately, though the amounts involved are modest relative to format retail alternatives.
What is the expected monthly revenue from an Oriflame franchise?
Monthly revenue for an Oriflame franchise is indicatively positioned between INR 50,000 and INR 2,00,000, with the actual figure determined primarily by the franchisee's network activity and customer retention rate. The lower end reflects a part-time or early-stage operation; the upper end reflects an active franchisee with an established recurring customer base and consistent outreach. Revenue ramp-up typically accelerates after the first three to four months as the customer pipeline builds.
Does Oriflame provide inventory on credit or consignment to franchisees?
Oriflame franchisees purchase inventory at the distributor price and own that stock from the point of order. The model is purchase-based rather than consignment, meaning inventory risk sits with the franchisee. At the investment levels involved, the exposure is limited, but it reinforces the importance of ordering in line with confirmed or anticipated demand rather than speculative range breadth.
What is the Oriflame franchise territory and exclusivity policy?
The Oriflame direct-selling model does not typically operate on the exclusive geographic territory allocation model used by format retail franchises. Multiple franchisees may operate in the same city or area, with each building their own customer network independently. For investors seeking formal territory exclusivity, this is a material point to clarify directly with Oriflame's franchise team before signing, as the competitive dynamics within a territory can affect long-term customer acquisition.
How many Oriflame franchise units are currently operating in India?
Oriflame's global network spans approximately 49,000 franchise units, with India representing one of the brand's significant direct-selling markets in Asia. The density of the Indian network means that consumer awareness of the Oriflame brand is substantially higher than newer or smaller beauty franchise entrants — an advantage that reduces the customer education burden for new franchisees entering the market.
Disclaimer: All scores, rankings, and estimates on ForeFind are independently produced editorial assessments using publicly available data and validated brand-submitted information. They are not verified facts, financial advice, or investment recommendations. Full Disclaimer.
