


Jabsons Foods Franchise: Investment, Returns and Profit Model in India
About Jabsons Foods
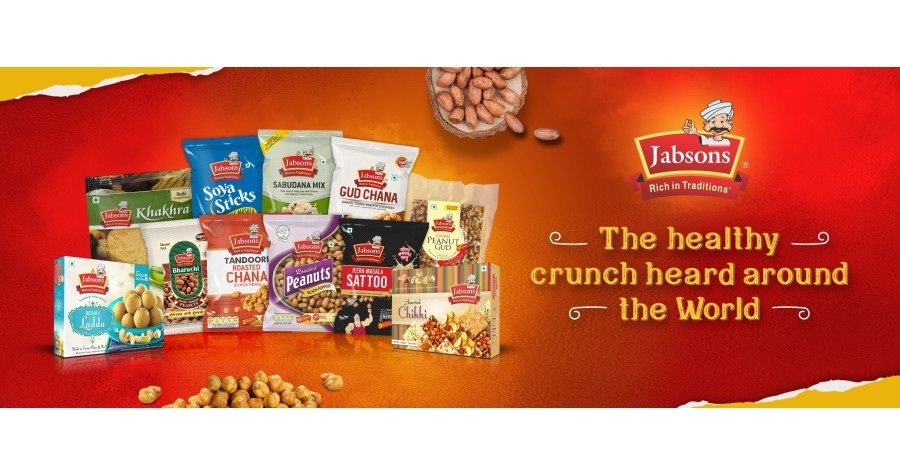
Jabsons Foods operates in the branded snacks and namkeen segment, selling its packaged range through a retail food mart format to both individual shoppers and bulk or institutional buyers. The snack business itself traces back to a much older industrial group with roots in cotton, ginning, and edible oil manufacturing dating to the early twentieth century, a lineage that eventually extended into food processing and packaged snacks. The franchise system built around this snack business has now run for 24 years, currently spanning ten to twenty operating units. That detail, a business with industrial roots reaching back more than a century and a snack-focused operation that has sustained franchising for nearly a quarter-century, is the fact worth anchoring an evaluation to: longevity here isn’t a marketing claim, it’s an operating record spanning multiple economic cycles.
The Revenue Model in Practice
A Jabsons Foods unit generates revenue primarily through retail sales of packaged snack products to walk-in customers, supplemented by bulk orders from smaller retailers, institutional buyers, or corporate clients purchasing in volume. This is a packaged-goods retail model rather than a prepared-food outlet, so there’s no kitchen output, no dine-in component, and no delivery-platform order stream to manage; the franchisee’s revenue depends almost entirely on footfall-driven retail turnover and the secondary B2B relationships they build locally. What the franchisee controls is store presentation, local stock mix decisions within the brand’s catalogue, and how actively they pursue bulk or institutional accounts beyond passive retail sales. What the system determines is product range, pricing structure, and packaging, all of which are set centrally to maintain consistency across the network.
Understanding the Investment: What INR 5 Lac – 10 Lac Actually Buys
At this investment level, the capital typically covers store fit-out for a 200 to 800 square foot retail space, initial stock inventory across the brand’s snack range, the franchise licensing fee, and working capital to sustain operations through the early months before sales stabilise. Unlike a prepared-food franchise, there’s no commercial kitchen equipment to fund, which keeps the setup cost contained relative to other food retail formats at a similar footprint. The ongoing monthly cost structure centres on rent for the retail space, wages for the two-to-eight staff handling sales and stock management, and regular inventory replenishment to keep shelf availability consistent. There is no delivery-platform commission line affecting margins here, since the model runs through direct retail and bulk sales rather than food delivery apps, though royalty or brand fee obligations, if applicable, should be confirmed directly with the franchisor as part of the total monthly cost picture.
Break-Even and Return Timeline
The nine-to-eighteen-month break-even window reflects how much variance exists in retail footfall and bulk account development across different locations and operators. Franchisees landing closer to nine months typically secure a location with strong organic retail footfall from day one and move quickly to add bulk or institutional buyers as a secondary revenue stream, rather than relying on walk-in sales alone. Those stretching toward eighteen months are usually managing a slower-footfall location or taking longer to build the bulk-order relationships that meaningfully boost revenue beyond retail-only sales. Within the franchisee’s control: location quality, local marketing effort, and how proactively they pursue B2B accounts. Outside their control: how much existing snack retail competition already exists in the chosen catchment area and regional consumption preferences for the brand’s specific product lines.
What the Franchisor Provides and What They Do Not
Jabsons Foods handles product manufacturing, packaging, and quality consistency centrally, along with brand recognition built over more than two decades in the snacks category. The brand has indicated it offers marketing and advertising support to franchisees, which can meaningfully reduce the local brand-building burden compared to launching an unbranded snack retail business from scratch. What remains with the franchisee is store-level execution: securing trade licensing and GST registration, hiring and managing retail staff, maintaining the physical store, and building bulk or institutional buyer relationships in their specific territory. The brand supplies product and some marketing backing; the franchisee supplies the local operating discipline and customer relationships that convert footfall into repeat business.
Financial Risk Factors Specific to This Category
Food spoilage risk is relatively low for packaged snacks compared to fresh food categories, though stock still needs rotation discipline to avoid holding inventory past its shelf life, particularly for products with shorter expiry windows. Delivery platform dependency is minimal given the retail-first model, which insulates margins from the commission structures that affect prepared-food franchises reliant on aggregator apps. Staff turnover carries a moderate cost here, mainly in lost product knowledge and customer rapport rather than anything more severe, since retail sales roles are easier to backfill than specialised food production roles. FSSAI-adjacent compliance and trade licensing remain the franchisee’s ongoing responsibility at the local level. Lease renegotiation is a real consideration at this footprint size; a 200 to 800 square foot retail space in a good-footfall location often sees rent escalate over a multi-year term, and franchisees should factor that into their margin planning rather than assuming flat costs throughout the lease period.
Who This Investment Suits and Who It Does Not
The franchisee most likely to reach break-even on the faster end secures a location with genuine organic footfall, actively manages stock and store presentation, and builds bulk or institutional accounts alongside retail sales rather than depending on walk-in traffic alone. They also bring enough local market awareness to choose a catchment area with real demand for branded snacks rather than one already saturated with competing options. The investor profile that consistently underperforms is the one treating this as a fully passive investment, selecting a location based on rent cost alone without assessing footfall or competition, and expecting brand recognition to compensate for limited personal involvement in the store’s day-to-day operation.
Accepting franchise applications in 33 states & UTs
Disclaimer: All scores, rankings, and estimates on ForeFind are independently produced editorial assessments using publicly available data and validated brand-submitted information. They are not verified facts, financial advice, or investment recommendations. Full Disclaimer.
