


Globe Capital Market Ltd. and the Indian Services Franchise Opportunity
A Globe Capital Market Ltd. franchise occupies a specific seam in India’s financial services landscape: the gap between national brokerages that operate purely through apps and call centers, and the retail investor who still wants a person they can sit across from. That gap matters most outside the metros, where a first-generation investor moving savings out of fixed deposits and gold into equities or mutual funds often needs someone to explain the basics before they’ll trust the platform. Globe Capital’s broking, depository, and distribution infrastructure already exists at scale; what the franchise model does is extend a local face onto that infrastructure in towns and city pockets that a centralized branch network can’t economically staff on its own. The franchisee isn’t building a brokerage from scratch — they’re licensing distribution rights to one that already clears meaningful volume on national exchanges, and applying it to a relationship the parent company can’t replicate without local presence.
Why Demand for This Service Is Structurally Growing in India
Three forces are pushing more Indian households toward formal investment advisory, and none of them are temporary. GST formalization pushed millions of small business owners into organized banking and tax reporting, which in turn surfaced surplus capital that previously sat idle or moved informally — capital that now needs a compliant home in mutual funds, equities, or structured products. Smartphone and UPI penetration did the cultural work of making digital financial transactions normal even in small towns, which lowered the psychological barrier to opening a trading or demat account. And regulatory tightening from SEBI and AMFI, while it raises the compliance bar for advisors, has simultaneously made the category more credible to a retail investor who was previously suspicious of anyone offering investment advice outside a bank branch. None of this is a post-pandemic blip or an interest-rate cycle; it’s the structural outcome of India’s savings pool shifting from physical assets to financial ones, a shift demographers and regulators expect to continue for at least another decade.
The Franchise Advantage Over Going Independent in This Service Category
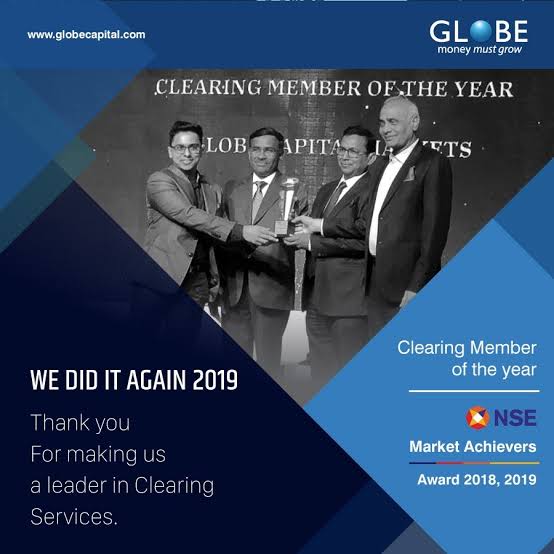
Anyone could, in theory, register as an independent sub-broker or advisor without a franchise agreement. What they’d be signing up to build alone is considerable: SEBI and AMFI registration processes that take real time and legal familiarity, a trading and depository technology stack that costs far more to build independently than to license, and — hardest to replicate — the credibility of an established brand name when a first-time investor is deciding whose office to walk into. Globe Capital’s national clearing volumes on the NSE and its depository participant status with NSDL and CDSL function as a trust signal that an independent advisor, however competent, takes years to earn solo. There’s also a quieter advantage in the peer network: a franchisee inside an established system can compare notes with hundreds of others who’ve already solved the same early-stage problems around client acquisition and local marketing, instead of learning everything by trial and error.
Territory, Market Sizing, and the Opportunity in Indian Cities
A typical Globe Capital franchise territory in a Tier 2 city covers a population base where even a conservative estimate puts tens of thousands of households with investable surplus beyond basic fixed deposits. The realistic addressable segment is narrower than that headline number suggests — it’s the subset actively curious about equities, mutual funds, or systematic investment plans but not yet committed to a specific advisor or platform. In the first two years, a franchisee converting even a few hundred of those households into active, servable accounts is a credible target, particularly given the network’s pace of adding roughly 125 new units annually across the country, which suggests the model scales predictably rather than requiring outsized local conditions to work. Penetration beyond that point depends less on market size and more on how consistently the franchisee shows up at the right local events, referral relationships, and community touchpoints.
Competitive Landscape: Who Else Serves This Market
The market splits into three tiers that rarely overlap well. Large discount brokers and bank-backed platforms dominate digital-first, self-directed investors who don’t want advisory hand-holding and are comfortable with app-only support. Independent local advisors and small sub-broker setups serve relationship-driven clients but often lack the compliance infrastructure and brand recognition to scale past a small personal network. Globe Capital’s franchise model sits in the space those two extremes leave open: clients who want a real local relationship but also want the assurance of a name with national clearing volumes and depository standing behind it. That’s a segment the discount platforms structurally can’t serve well, since their economics depend on minimizing human touch, and that the smallest independents struggle to serve consistently, since their capacity and credibility cap out quickly without institutional backing.
The Recurring Revenue Advantage of This Business Model
Financial advisory and broking franchises earn differently from most low-investment services categories, where revenue is largely one-off and project-based. A meaningful share of a Globe Capital franchisee’s income comes from brokerage on ongoing trading activity, trail commissions on mutual fund holdings, and advisory relationships that renew implicitly every time a client makes another investment decision rather than walking away after a single transaction. That structure is what makes the franchise’s break-even window of two to four months plausible even with modest staffing: the business isn’t waiting on new sales every month to survive, it’s compounding a client base whose existing holdings keep generating revenue quietly in the background. Over several years, that recurring layer is what turns a franchise from a job replacement into an asset with resale or succession value, since a buyer is effectively purchasing a book of ongoing relationships rather than a one-time client list.
Who Captures the Most Value From a Globe Capital Market Ltd. Franchise
The franchisees extracting the most value from this model typically combine three things: enough finance fluency to be credible in a client conversation without leaning entirely on scripted material, an existing local network — community ties, professional associations, family business circles — that shortens the trust-building timeline, and the discipline to treat client servicing as a non-negotiable weekly habit rather than something done only when chasing a new sale. That combination is what makes the franchise defensible against new entrants. Anyone can register as a broker; far fewer people can show up consistently enough, with enough credibility, to become the person a town’s small investors call first.
Accepting franchise applications in 32 states & UTs
How does Globe Capital Market Ltd. compare to starting an independent practice in this service category?
An independent practice requires building SEBI and AMFI compliance processes, trading technology, and brand credibility entirely from scratch, which typically takes years and significant capital before reaching client trust levels a franchise starts with on day one. The Globe Capital Market Ltd. franchise compresses that timeline by providing the regulatory framework, technology platform, and brand recognition upfront.
What is the addressable market size for Globe Capital Market Ltd.'s services in a typical Indian city?
A Tier 2 Indian city typically contains tens of thousands of households with investable surplus beyond traditional savings instruments, though the realistically addressable segment is narrower — households actively open to equity or mutual fund advisory but not yet locked into an existing provider.
Does Globe Capital Market Ltd. compete with large corporate service providers or serve a different segment?
It serves a distinct segment: clients who want personal, local advisory relationships rather than purely digital self-service. Large discount brokers optimize for low-touch digital users, leaving relationship-seeking investors as a segment Globe Capital's franchise network is positioned to serve more directly.
What is the client retention rate in the Globe Capital Market Ltd. franchise network?
Retention in this category is driven by ongoing portfolio servicing and trail-commission relationships rather than one-time transactions, which structurally favors long client tenures when franchisees maintain regular contact, particularly during volatile market periods when clients most need reassurance.
How is Globe Capital Market Ltd.'s territory exclusivity structured?
Territories are typically allocated to avoid direct overlap between franchisees in the same local market, allowing each franchise to build a defined client base within their geography without competing against another unit from the same network.
Disclaimer: All scores, rankings, and estimates on ForeFind are independently produced editorial assessments using publicly available data and validated brand-submitted information. They are not verified facts, financial advice, or investment recommendations. Full Disclaimer.
