


Sgl Miniplex Private Limited Franchise: India’s Travel and Hospitality Market, Demand Drivers and Competitive Positioning
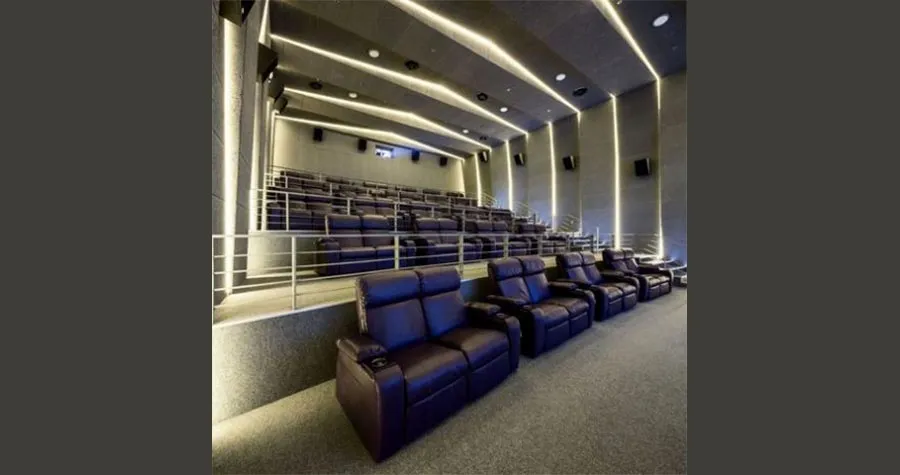
The Sgl Miniplex Private Limited franchise operates in cinema exhibition, specifically the miniplex format built to bring multiplex-grade comfort to district and smaller-city markets at a lower capital footprint than a full-scale multiplex. Categorised under travel and leisure, its real positioning sits within organised entertainment infrastructure for non-metro India, a segment that has expanded as smaller cities have moved away from ageing single-screen theatres toward branded, technology-driven cinema experiences.
Sgl Miniplex Private Limited in the Context of India’s Travel and Hospitality Growth
India’s leisure spending has steadily shifted toward organised formats over recent decades, and cinema exhibition outside the major metros has been a clear beneficiary of that shift. The miniplex format this brand operates under was built specifically to serve audiences in district-level markets who want a comfortable, modern viewing experience without the scale and cost of a full multiplex. With 33 years in franchising behind it, the brand has operated through multiple cycles of change in Indian cinema technology and audience preference, which positions it differently from newer entrants still establishing their operating model.
Why Travel and Hospitality Demand Is Structurally Growing in India
Three structural forces support continued growth in this category. Rising disposable incomes in smaller cities have expanded the audience willing to pay for a premium, air-conditioned cinema experience rather than an older single-screen alternative. Leisure activity in India has broadened well beyond traditional pilgrimage-driven travel, with district towns increasingly functioning as regional centres for family outings and entertainment spending. And there remains a persistent undersupply of organised, comfortable entertainment venues outside metro markets, leaving local demand to be served by either ageing single screens or nothing at all. The miniplex format addresses this last point directly, positioning itself in towns large enough to support demand but too small to justify a full multiplex investment.
What the Sgl Miniplex Private Limited Franchise Provides That Independent Operators Cannot Match
An independent cinema operator entering a district market alone has to source digital projection and sound technology, negotiate film distribution access without an established track record, and build the operational playbook for running a screen from scratch — a slow process with no guarantee of getting technical specifications right the first time. A franchise under this brand carries decades of accumulated experience in digital film delivery, sound and projection standards, and distribution relationships that an independent operator would need years to replicate. This advantage compounds in smaller markets, where the franchisor’s existing relationships with film distributors and technology vendors translate into faster, more reliable access than a standalone operator could secure on their own.
Geographic Opportunity: Where Sgl Miniplex Private Limited Is Expanding in India
With only ten locations operational against a long-stated ambition to establish a presence in districts across the country, the clearest remaining opportunity lies in district headquarters and growing Tier 2 towns that currently have no organised, comfortable cinema option. These markets typically combine enough population density to support steady footfall with almost no competing branded format, unlike metro markets where multiplex chains have already saturated demand. The brand’s measured pace of under one new unit per year suggests expansion has prioritised getting each location’s economics right over rapid, undisciplined rollout — a pattern consistent with a long-operating brand cautious about overextending into markets that cannot sustain a high-investment format.
Online Disruption and How Sgl Miniplex Private Limited Is Positioned
The disruption pressure most relevant to cinema exhibition comes from streaming and OTT platforms rather than online travel aggregators, and this brand’s positioning treats that pressure as something to coexist with rather than compete against directly. A miniplex venue offers a communal, big-screen experience in towns where streaming has not eliminated the appeal of stepping out for an evening, particularly when ticket pricing stays accessible relative to metro multiplexes. Rather than serving the same audience streaming already captures at home, this format serves the segment that values an affordable outing experience streaming cannot replicate.
Competitive Differentiation in an Increasingly Crowded Market
Against both larger multiplex chains and unbranded local cinemas, this franchise’s differentiation rests on offering a multiplex-equivalent comfort level — proper seating, climate control, quality sound — at a lower capital and operating cost than a full multiplex requires, which makes the format viable in towns a larger chain would consider too small to enter. Against an independent local cinema, the advantage is consistency: standardised projection quality, digital content delivery, and a recognisable brand identity that audiences come to trust over repeated visits. In smaller markets, that combination of affordability and consistency is what makes the format harder to displace once established.
Who Builds a Profitable Sgl Miniplex Private Limited Franchise
Given the scale of investment and staffing this format demands, the franchisees who build the most resilient operations typically combine local community standing with the ability to develop relationships beyond individual ticket sales — schools, local businesses, and community organisations that can be converted into group bookings or event screenings. In a market where the venue itself may be the first organised cinema many residents have access to, relationship capital and local visibility tend to matter more than aggressive marketing spend in determining how quickly the location builds a loyal, repeat audience.
Accepting franchise applications in 35 states & UTs
How does Sgl Miniplex Private Limited compete with online travel aggregators in India?
As a cinema exhibition format, the relevant competitive pressure comes from streaming platforms rather than travel aggregators, and the brand's positioning leans on the in-person, communal viewing experience that streaming does not replicate.
Is a Sgl Miniplex Private Limited franchise viable in Tier 2 and Tier 3 Indian cities?
Yes. The miniplex format was specifically designed for district-level and Tier 2 markets, where organised cinema infrastructure remains limited and demand continues to grow alongside rising local incomes.
What is the impact of seasonality on Sgl Miniplex Private Limited franchise revenue?
Cinema exhibition carries relatively low seasonality, with revenue patterns tied more closely to the film release calendar and festive periods than to fixed seasonal cycles.
How does Sgl Miniplex Private Limited support franchisees in building corporate travel accounts?
Since the format centres on cinema exhibition rather than travel booking, the more relevant support lies in content access and technical infrastructure, while local relationship-building for group and institutional bookings remains the franchisee's responsibility.
What is Sgl Miniplex Private Limited's expansion strategy for India over the next two years?
Expansion is expected to continue at a measured pace, focusing on district headquarters and Tier 2 cities that remain underserved by organised, comfortable cinema formats.
Disclaimer: All scores, rankings, and estimates on ForeFind are independently produced editorial assessments using publicly available data and validated brand-submitted information. They are not verified facts, financial advice, or investment recommendations. Full Disclaimer.
