


Livspace Franchise: Urban Demand, Market Position and Growth Opportunity in India’s Home Services Sector
The Livspace franchise enters India’s home services market from a position built over a decade of operating in one of the country’s most trust-sensitive categories: home interior design and renovation. Founded in 2015 and now active across India, Singapore, and Malaysia, Livspace has developed a franchise model that addresses the central problem consumers face when renovating their homes — the gap between what an independent contractor promises and what actually gets delivered. For investors evaluating the construction and renovation segment, understanding where Livspace sits in the competitive hierarchy requires understanding what that trust gap costs consumers who navigate the unorganised market without it.
Livspace and India’s Organised Home Services Opportunity
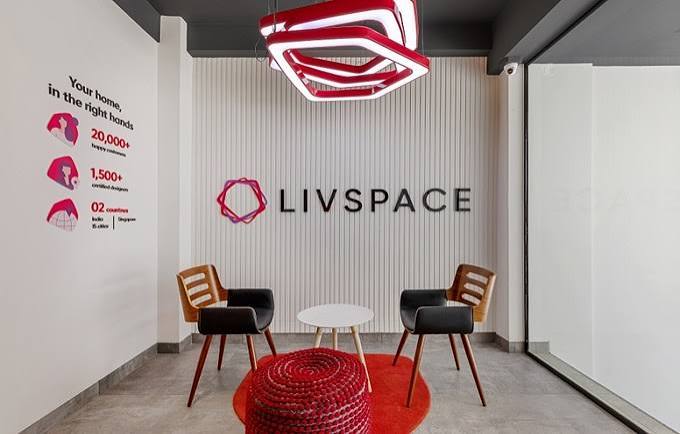
Livspace operates as a managed home interior solution — handling material procurement, design, contractor coordination, and project delivery under a single accountable entity. This is structurally different from a contractor who builds, a materials supplier who sells, or a designer who specifies but does not execute. The franchise model takes this integrated approach and replicates it across geographies, giving each franchisee the operational systems, material standards, and brand association needed to deliver a consistent service in a category where consistency has historically been the exception rather than the rule.
The trust gap in unorganised home renovation is well-documented by anyone who has attempted it. Contractors disappear mid-project, material substitutions happen without consent, timelines expand without explanation, and the homeowner has no recourse because nothing was formally guaranteed. Livspace’s franchise infrastructure — quality-checked materials including plywood, hardware, and laminates calibrated to Indian and European standards — provides the accountability layer that changes this dynamic fundamentally.
Why Demand for Organised Home Services Is Growing in Urban India
Three converging trends have expanded the addressable market for organised home interior services faster than the supply side has been able to keep up with. First, dual-income nuclear households now dominate urban India’s middle class. These households have the purchasing power to pay for renovation but neither the time nor the extended-family network to manage an unorganised contractor relationship across months of back-and-forth. They want a managed outcome, not a project management role.
Second, apartment living has become the dominant housing format across Indian cities of all tiers. Apartment owners renovate within defined parameters — floor, walls, kitchen, bathrooms — which makes the interior renovation scope both standardised and recurring across a building’s lifecycle. Every new possession, every resale, every tenant changeover is a potential Livspace engagement. Third, smartphone-native consumers now expect service discovery, booking, communication, and quality feedback to happen digitally. Brands that meet this expectation structurally — rather than relying on word-of-mouth alone — are disproportionately capturing the organised segment’s growth.
The Franchise Advantage Over Independent Home Service Operators
An independent home interior operator competing in the same market as a Livspace franchisee faces a specific set of structural disadvantages that compound over time rather than diminishing. Brand recognition is the first: a consumer researching renovation options online encounters Livspace’s national digital presence before they encounter any local independent. The franchisee benefits from this visibility without having funded it.
Material sourcing is the second disadvantage. Livspace’s centralised procurement model means franchisees access plywood, laminates, hardware, and finishing materials at costs that reflect group purchasing volumes. An independent operator sourcing the same quality individually pays retail or near-retail prices, which either compresses margins or forces a price premium the market may not accept. The technology layer — project tracking, client communication, design tools, and quality checklists — would cost an independent operator both capital and sustained maintenance investment to replicate. A Livspace franchisee inherits this infrastructure from onboarding day, allowing operational focus on execution and client relationships rather than system-building.
Geographic Opportunity: Where Demand Is Strongest and Under-Served
Organised home interior penetration remains highest in India’s top six metros, where brand awareness is deepest and consumer willingness to pay for verified services is most established. But the fastest growth in this category is happening elsewhere. Tier 2 cities — Lucknow, Indore, Coimbatore, Vadodara, Nagpur, and similar markets — are experiencing their first wave of organised home services demand as real estate development accelerates and consumer expectations migrate from metro exposure via media and travel.
With ten operational units in the current Livspace franchise network, the geographic white space across India’s 50-plus cities with populations above five lakh is substantial. Franchisees entering a Tier 2 city today are not competing against an established local Livspace presence; they are building it. First-mover positioning in a growing organised market compounds over time as referral networks develop and the brand name becomes associated with quality renovation in that geography.
Competitive Landscape: Aggregators, Independents, and Branded Franchises
Three models compete for the organised home renovation consumer in India. Digital aggregator platforms connect consumers with independent service providers, generating lead volume but offering no quality guarantee beyond review scores. The consumer still bears the risk of a poor contractor relationship. Unorganised independents — individual contractors and small teams — offer local familiarity and price flexibility but no accountability infrastructure. Branded franchise networks like Livspace sit in a third position: they carry the quality assurance and brand trust that aggregators cannot provide, combined with the local presence and personalised service that a national platform cannot replicate.
The franchise model’s structural advantage over aggregators is accountability. A franchisee’s business depends on local reputation in a way that a contractor listing on an aggregator platform does not. The franchisee cannot disappear, cannot substitute materials without consequence, and cannot leave a project incomplete without affecting their own ongoing commercial livelihood. This accountability is visible to consumers, and it is what converts initial brand recognition into actual bookings.
The Recurring Revenue Model and Long-Term Client Value
Home interior projects are not one-time transactions for most households. A kitchen renovation is followed years later by bathroom upgrades, then bedroom refurbishment, then another kitchen cycle. A client who experiences a well-managed first project with a Livspace franchisee becomes the most cost-efficient revenue source that franchisee will ever have: no acquisition cost, high trust, and a predictable repeat cycle. The long-term value of a managed client relationship in this category significantly exceeds the revenue from any individual project.
The franchise unit’s value as a business asset also reflects this dynamic. A franchisee with a strong local client base and an active referral network is operating a business with forward revenue visibility — not one that resets to zero after every project. Building that client base takes twelve to twenty-four months of consistent delivery, which is why the break-even timeline reflects investment in relationship capital as much as operational cost recovery.
Who Captures the Most Value From a Livspace Franchise
The franchisees who build the most productive Livspace businesses share a characteristic that no amount of capital can substitute: they are genuinely embedded in their local community and treat every project as a public demonstration of their personal standards. In home services, a satisfied client tells four or five people. A dissatisfied one tells more. The franchisee who understands this arithmetic invests in service quality not as a cost of compliance but as the primary growth mechanism.
Geographic rootedness matters in this category because renovation decisions are still heavily influenced by personal recommendation. A franchisee who has lived in their city for a decade, knows the right architects and real estate agents, and has a visible commercial presence will convert referrals at a rate that an out-of-market investor managing the business at a distance will not. The Livspace franchise rewards operators who treat their local reputation as the asset — because in home services, it is.
How does Livspace compare to home service aggregator platforms for franchisees?
Aggregator platforms generate leads but transfer service delivery risk entirely to the individual contractor. A franchisee listed on an aggregator is competing on price and review score against hundreds of unbranded competitors. A Livspace franchisee operates under a brand that carries its own consumer recognition, material quality standards, and project management infrastructure — which changes the competitive conversation from price to value. The franchise model also builds local equity over time in a way that aggregator participation does not.
Is a Livspace franchise viable outside of metro cities?
Tier 2 cities represent some of the strongest current opportunity for a Livspace franchise, precisely because organised competition is limited and consumer demand for accountable home interior services is growing. The middle-class renovation market in cities like Indore, Coimbatore, or Nagpur is at an earlier stage of maturity than Mumbai or Bengaluru — which means franchisees entering now face less competition and greater first-mover advantage than they would in a saturated metro market.
What is the addressable market size for Livspace's service in a typical Indian city?
In any Indian city with a population above five lakh, the addressable market for organised home interior services includes new apartment possessions, resale property renovations, rental property upgrades, and commercial interior projects. The organised segment — consumers willing to pay a premium for a brand-accountable provider over an unverified independent — represents a growing fraction of this total as consumer expectations evolve. The specific market size in a target city is best assessed through the brand's franchise development process, which includes territory evaluation as part of onboarding.
How does Livspace differentiate from unorganised independent service providers?
The differentiation operates at three levels. Material standards: Livspace's product range is quality-checked against defined benchmarks, which removes the substitution risk that plagues unorganised contractor relationships. Project accountability: the franchisee is a commercially accountable entity with reputational and contractual skin in the game, unlike an independent contractor whose leverage disappears once work has begun. And post-project support: the brand's systems for follow-up and complaint resolution give clients a recourse channel that simply does not exist in the unorganised market.
What is Livspace's client acquisition model for new franchisees?
New Livspace franchisees benefit from the brand's national digital presence as a baseline, which generates awareness in markets where the brand name is already known. At the local level, client acquisition in the first twelve months is driven by professional outreach to architects, interior designers, real estate agents, and housing society networks — relationships that generate referrals rather than one-time transactions. The brand provides marketing assets and lead generation tools, while local relationship-building remains the franchisee's primary acquisition strategy. Specific support mechanisms are detailed during the formal franchise inquiry and onboarding process.
Disclaimer: All scores, rankings, and estimates on ForeFind are independently produced editorial assessments using publicly available data and validated brand-submitted information. They are not verified facts, financial advice, or investment recommendations. Full Disclaimer.
