


Bro Gourmet Factory Franchise: Market Position, Category Opportunity and Competitive Edge
Bro Gourmet Factory and Where It Fits in India’s Food Franchise Landscape
The Bro Gourmet Factory franchise occupies a specific and deliberate position in India’s food service market: a cloud kitchen and catering format built around home-style food, operating without the traditional chef dependency that makes restaurant ownership prohibitively complex for most first-time business owners. The model targets individual consumers and corporate clients simultaneously, which diversifies revenue exposure in a way that single-channel food outlets cannot replicate. Priced within a range accessible to family-backed investors and young professionals, it sits below the capital threshold of full-service restaurant franchises while offering more structural support than an independent food business would. What makes this position defensible is the format’s deliberate removal of the two variables that most often sink small food businesses: the skilled chef requirement and the high-cost physical premises.
Why This Food Format Is Growing in India Right Now
Several structural shifts in the Indian economy are converging in ways that benefit cloud kitchen and catering formats specifically. Disposable incomes in Tier 2 cities have risen steadily, and with that rise has come a shift in food consumption behaviour — households that previously cooked all meals at home are now ordering out two to four times a week. Delivery platform adoption in cities like Coimbatore, Indore, Kochi, and Nagpur has reached levels that sustain consistent daily order volumes for well-positioned outlets.
The second driver is demographic. Dual-income households — where both partners work full-time — generate sustained demand for reliable, consistent, home-style food at accessible prices. This is a different customer from the weekend dining-out crowd; they are placing orders on Tuesday evenings and weekday lunches, which is precisely the demand window that cloud kitchen formats are structured to serve. Simultaneously, Indian consumers at every income level are moving away from unbranded, unverified local food options toward formats that signal hygiene, consistency, and accountability — a shift that FSSAI visibility and branded packaging reinforce.
What Bro Gourmet Factory Does Differently From Independent Food Outlets
Opening an independent food business in India requires solving several problems simultaneously: building a menu that sells, establishing supply relationships, creating delivery platform accounts and maintaining ratings, training staff without any operational template, and managing customer expectations without brand equity to fall back on. Most independent food businesses fail within the first eighteen months because solving all of these problems at once while also running daily operations exceeds the capacity of a single owner.
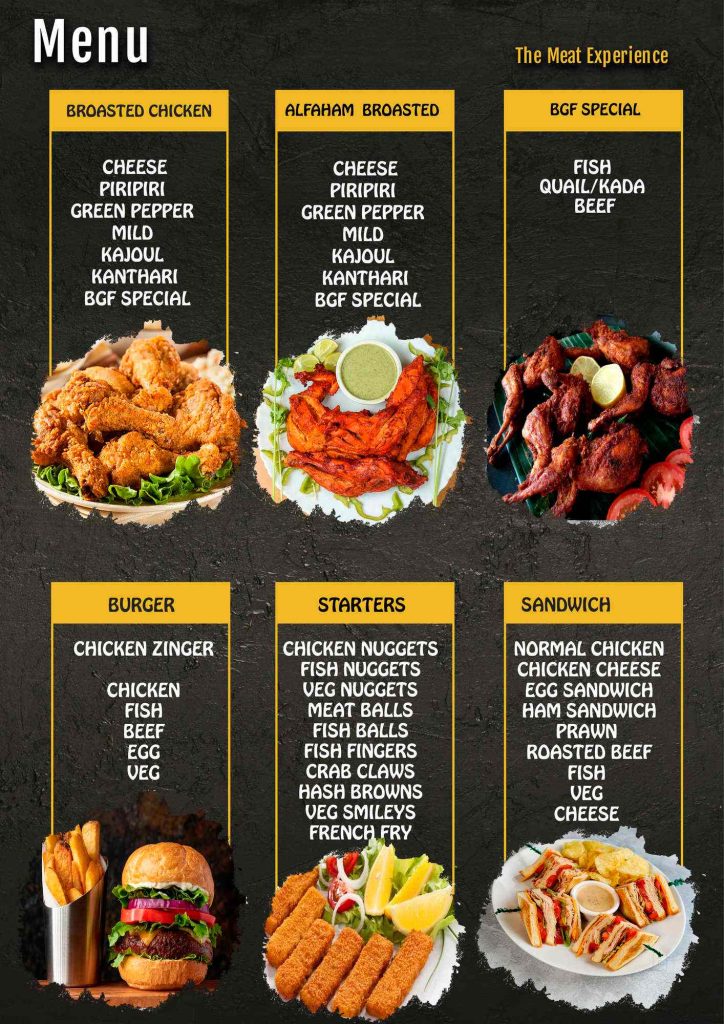
Bro Gourmet Factory transfers several of those problems to the franchisor. The menu is already developed and tested. Operational systems exist in documented form. Delivery platform integration is part of the onboarding process rather than a post-launch task. The brand’s presence across multiple cloud kitchen locations in its operating markets creates a recognition baseline that a new independent outlet cannot manufacture in the short term. For an investor who wants to run a food business without building one from scratch, the value is in what does not need to be created.
The Investment Case: How Bro Gourmet Factory Compares at This Price Point
Within the INR 50,000 to 5 lakh investment band, the food franchise category offers a wide range of options — most of them either single-product kiosks with limited revenue ceiling or underdeveloped concepts with minimal operational support. Bro Gourmet Factory’s positioning as a B2B and B2C operator within a 200 to 300 square foot footprint allows for a revenue mix that single-format competitors in this range cannot access. The catering and corporate supply channel, in particular, generates order volumes that walk-in and delivery-only formats structurally cannot.
The estimated break-even window of 9 to 18 months is consistent with well-managed QSR and cloud kitchen formats in the Indian market. What differentiates outcomes within that window is not the brand — it is the franchisee’s local market activation. The network of ten operational units provides a reference base for evaluating how the model performs across different city types, which is more useful to a prospective investor than projections derived from theoretical models.
Geographic Opportunity: Where Bro Gourmet Factory Is Expanding
Ten operational units represents early-stage coverage by any measure. The majority of India’s Tier 2 and Tier 3 cities — where delivery infrastructure has matured but branded cloud kitchen penetration remains low — represent the clearest white space for this format. Cities with populations between 500,000 and 2 million typically have active Swiggy and Zomato ecosystems but far fewer branded food options than metros, which means a new entrant with a recognisable identity and consistent product competes against independent operators rather than established franchise networks.
Territory allocation terms should be confirmed directly with the franchisor, as early-stage brands typically negotiate territory on a case-by-case basis. Investors in underserved markets have a first-mover advantage that diminishes as the network grows, making this a relevant timing consideration for anyone evaluating the opportunity now versus in two years.
The Risks of This Category and How Bro Gourmet Factory Mitigates Them
Delivery platform commission pressure is the most persistent financial risk in cloud kitchen operations — aggregators take between 18 and 30 percent of order value, which compresses margins on delivery-only revenue. Bro Gourmet Factory’s B2B catering channel partially offsets this by generating direct corporate orders that bypass platform fees entirely. The degree of mitigation depends on how actively the franchisee develops that channel.
Raw material cost volatility affects every food business, and cloud kitchen formats are not exempt. Centralised supply or standardised sourcing protocols reduce this risk compared to fully independent procurement. FSSAI compliance is a non-negotiable operational requirement; the licensing process is manageable for a single-unit operator but requires consistent documentation and renewal discipline. Location selection within a no-fixed-location model shifts site risk toward the franchisee — a poorly chosen area with low delivery density will underperform regardless of operational quality. Franchisees should assess delivery order volume in their target area before committing to a specific location.
Who Captures the Most Value From a Bro Gourmet Factory Franchise
The franchisee who reaches break-even at the shorter end of the 9 to 18 month range shares a consistent profile across food franchise formats at this scale. They are present at the outlet during service hours, not managing it remotely. They know their delivery platform dashboards well enough to identify which menu items drive ratings and which suppress them. Critically, they activate the B2B channel early — approaching nearby offices, small corporate parks, and local event organisers within the first 60 days — rather than waiting for the B2C side to stabilise first.
Community presence matters more than most investors expect. A franchisee who is known locally, who resolves complaints directly and quickly, and who treats repeat customers as relationships rather than transactions builds the word-of-mouth that no marketing spend at this budget level can replicate. Investors who treat a Bro Gourmet Factory franchise as a managed asset rather than an active business consistently take longer to break even, because the model requires daily operational attention to reach the throughput that justifies the investment.
Disclaimer: All scores, rankings, and estimates on ForeFind are independently produced editorial assessments using publicly available data and validated brand-submitted information. They are not verified facts, financial advice, or investment recommendations. Full Disclaimer.
